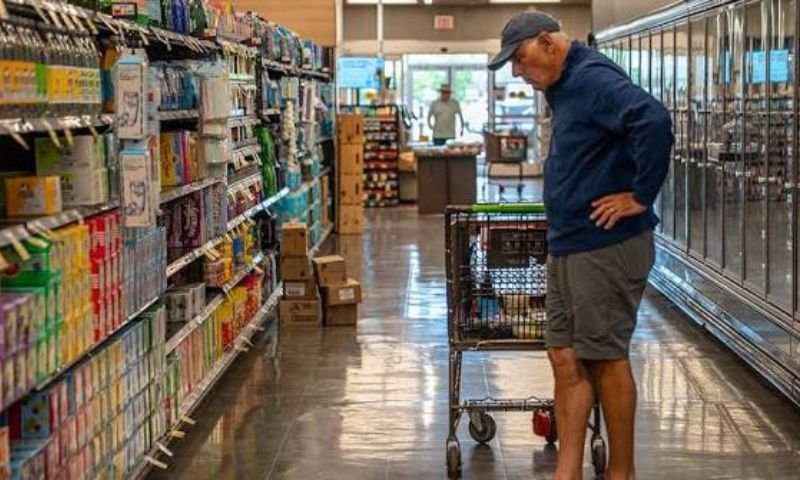
Across America, millions of households are working to exhaustion while banks, insurers, lenders and corporate platforms collect their share before families can save anything.
Mortgage payments fall due, followed by car payments, insurance premiums, utility bills, credit-card interest, protection plans and subscriptions. After paying for housing, transportation and other essentials, little may remain for savings, children’s education or retirement. Work continues, but financial freedom retreats.
At the other end of these payment chains, wealth accumulates on a scale ordinary wage earners can hardly imagine. Families struggle to decide which bill can wait, while the fortunes of the wealthiest grow by billions.
America has become extraordinarily successful at creating immense private fortunes, but it has failed to protect many of the people who sustain its prosperity from persistent financial insecurity.
Forbes’ March 2026 ranking placed 15 of the world’s 20 richest people in the United States. Its September assessment valued the country’s 400 wealthiest people at a combined $8 trillion, up from $6.6 trillion a year earlier. The richest 20 Americans alone held approximately $4 trillion.
These estimates measure assets, not money taken directly from households, but they reveal the extraordinary concentration of wealth at the top.
Meanwhile, the US Census Bureau counted 34.5 million Americans below the official poverty line in 2025, representing 10.2 percent of the population. Its broader Supplemental Poverty Measure, which accounts for taxes, benefits and expenses such as medical and work-related costs, put poverty at 13.1 percent.
Financial insecurity extends beyond these figures. A household can earn too much to be classified as poor and still have too little left after essential bills to withstand illness, unemployment or a major repair.
That is the dividing line this article examines: the difference between earning an income and retaining enough of it to build a secure life. The Federal Reserve found that 91 percent of adults were concerned about prices in 2025.
Only 63 percent said they could cover a $400 emergency entirely with cash or its equivalent, while 26 percent reported skipping medical care because of cost. A wealthy national economy can coexist with deeply insecure household budgets.
The pressure is cumulative. Housing ties income to rent or a mortgage, while employment may require a car, bringing financing, insurance, fuel and repair costs. High medical prices make insurance essential, yet premiums and out-of-pocket expenses add to the burden. Credit covers shortfalls but creates further interest charges.
Subscriptions and service contracts then claim smaller portions of what remains. Each institution sees its own transaction, while families must manage their combined costs.
The central question is how much income households can retain after paying for the necessities of American life. When essential services become increasingly expensive and access depends on continuous payments, corporate revenues can rise while the people generating them lose their ability to save.
Housing is the first claim on income. According to the US Census Bureau, median monthly owner costs for households with a mortgage reached $2,035 in 2024, including selected expenses such as insurance, taxes and utilities.
Median gross rent was $1,487. These are national figures, and individual households may face much higher bills. Before families buy food or save for their children’s future, shelter has already taken a substantial share of their earnings.
Transportation creates another chain of obligations. In Michigan, where we live and work, public transport does not adequately connect our family members’ workplaces and schedules.
Four people travelling in different directions can create a need for several vehicles. Each brings costs such as loan payments, fuel, registration, repairs and insurance. Transportation thus becomes part of the cost of holding a job.
Michigan requires no-fault insurance for vehicles driven legally. Lenders may also require additional protection for financed cars. Homeowners insurance is generally a mortgage requirement, while life insurance, extended warranties and shopping memberships are ordinarily optional.
These distinctions matter, but households experience the cumulative burden regardless of whether expenses originate in legislation, lending contracts or personal decisions.
The Bureau of Labor Statistics offers a revealing national comparison. In 2024, housing accounted for 33.4 percent of average consumer expenditure, while transportation accounted for another 17 percent.
Together, they absorbed just over half of spending. Food accounted for 12.9 percent. Our experience of groceries representing a relatively small part of the financial pressure is therefore plausible: the largest burdens often arrive before shopping begins.
Healthcare makes the pressure more formidable. KFF found that average annual premiums for employer-sponsored family health coverage reached $26,993 in 2025. Workers contributed an average of $6,850, with employers paying the balance.
Although the entire premium does not come directly out of workers’ paychecks, the employer contribution remains part of the cost of employing them.
Even after insurance coverage is purchased, deductibles, copayments and uncovered services may remain. Dental and vision benefits are frequently arranged separately. Families can therefore pay repeatedly for protection and still face significant bills when they need treatment.
Insurance provides genuine protection against losses that savings alone may not cover. A year without a claim does not mean the protection had no value. The deeper problem is that when treatment, repairs or replacements become prohibitively expensive, households grow increasingly dependent on intermediaries to afford these services.
Lowering the cost of care would benefit insured families and those struggling to obtain coverage.
The scale of America’s financial machinery is enormous. The National Association of Insurance Commissioners’ report covering 2024 recorded 6,228 domestic insurance companies and approximately $3.65 trillion in premiums and deposits.
This figure includes commercial business, annuities and deposit-type funds; it represents neither household spending alone nor industry profit. Nevertheless, it demonstrates the scale of economic activity passing through institutions that sell financial protection.
Protection is also sold in additional layers. Industry estimates put the number of US home-warranty providers at 78, with $4.3 billion in revenue in 2024. Auto extended-warranty providers numbered approximately 287 in 2024, while their market was estimated at $22 billion in 2025. Appliance, electronics and phone protection plans extend this model further.
Their prices may appear modest compared with a mortgage, but each represents another recurring commitment competing with savings.
Credit provides relief today by reserving part of tomorrow’s earnings. At the end of 2025, the United States had 4,336 FDIC-insured banks and savings institutions and 4,287 federally insured credit unions. Their combined reported net income was approximately $314.4 billion.
Their activities include business lending and other services, so this figure cannot be described as profit extracted exclusively from households. However, it illustrates the scale of the institutions through which families finance major purchases and manage financial shortfalls.
Mortgages require the same accounting discipline. The latest official dataset covered 4,782 institutions reporting mortgage activity in 2025. The Mortgage Bankers Association’s October 2026 forecast put single-family mortgage originations that year at approximately $2.1 trillion.
The principal advanced is not lenders’ revenue; interest, fees, servicing and loan-sale income are the relevant earnings streams. United Wholesale Mortgage, for example, originated $163.4 billion in loans in 2025 and reported $3.16 billion in revenue.